Author: Wribhu

  • Factory and Lab mindsets in product management teams

    Factory and Lab mindsets in product management teams

    Factories and laboratories evoke very different images.

    With a factory – I am usually thinking the industrial revolution in all its glory – machines, assembly lines, robots, workers, all working in a disciplined and predictable manner – churning out products that are all identical and meet the claimed specifications. Low room for error. Designed for scale.

    On the other hand, when I think of a lab – I usually come up with a white coat wearing team of specialists pouring over data. Going deeper into a topic. Asking fundamental questions. Pushing boundaries. New ideas being discussed and prototyped.

    While I know these are extremely simplified and probably exaggerated views, they are helpful in defining what I call as the Factory Mindset and the Lab Mindset. So bear with me.

    The Factory and Lab Mindset

    The Factory mindset or culture is where the blueprint has been validated and chosen for at scale business. Think of this as the mindset needed to to do more of the same thing at the right cost, quality – a highly process oriented approach.

    And this is relevant in the service sector too. Think of a bank branch, or the claims underwriting team of an insurance co. The rule book, processes, roles and responsibilities are all clearly laid out. Thereby ensuring that customer after customer can be duly served.

    The Lab mindset is what triggers change and innovation. It requires the ability to challenge the status quo. To ask fundamental questions, build hypotheses. Be bold enough to experiment with some of those hypotheses. And be ready to fail.

    Need for both mindsets to co-exist

    In today’s fast changing business environment, its imperative to nurture both these mindsets/cultures concurrently. More so within the product team(s) at consumer/enterprise technology companies.

    And it’s tough !

    In any multi-product organization, chances are that the products are at various stages of their lifecycle. Some might be in a MVP or Pre-commercialization stage, while (hopefully) most are on a scale-up path in the commercialization stage and few others may be close to the end of their life cycle.

    Sarah is a product manager focused on an early stage product. She needs to be like a scientist – doing experiments, tracking whats working and what’s not and getting the product to evolve rapidly. More importantly her manager needs to guide, motivate and evaluate like a senior scientist would. The Lab mindset needs to prevail.

    Contrast this with Peter, who’s product contributes to almost 15% of all revenues. A big part of his job is to keep the commercialization machinery humming. From updating pitch decks, to reviewing the pricing model, understanding the sales pipeline – its a very different role he plays. He also does some of what Sarah does full-time. Peter needs to have a close pulse of the market – understand the current pain-points, evolving consumer needs and build or modify features/functionalities to keep the product relevant.

    This ability to toggle across the Factory and the Lab mindsets is critical for organizations and individuals to keep innovating, evolving and staying relevant while still growing.

    Do you agree?

    If you do, how do you think organizations should be designed to nurture this co-existence of seemingly different cultures and mindsets? Share how your organization does it well already. Because I feel this is more fundamental than just having different kinds of performance metrics depending on the stage of the product.

    If you have found a way to do this well at your individual level please do share.

    Going back to the earlier visualizations, isn’t it hard to imagine a lab-coat wearing nerdie walking around the factory floor? I remember from my engineering summer internship – the R&D deptt was in an air-conditioned separate section of the plant. The deptt infact had its own assembly line to make shock-absorbers!
  • Quest for Friction Less Experiences

    Quest for Friction Less Experiences

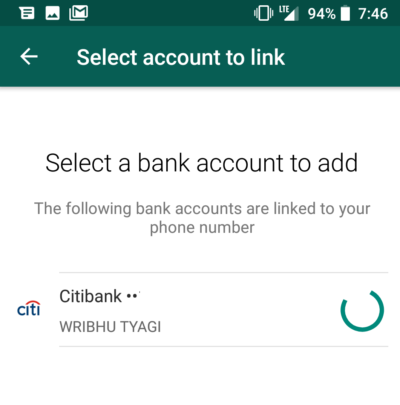
    Yesterday, I got to experience the WhatsApp payment flows. It surely felt like a neat friction-less experience both for adding/mapping bank accounts and for in-chat payments.

    And in my excitement I forwarded it to a friend who didn’t have any UPI handle so far. And I was surprised by the reaction.

    How does WhatsApp know my bank account ??!! 

    Payment friction

    And frankly I had looked at it the other way round – they are showing me the specific account that I want to associate here.

    And this got me thinking about friction in digital consumer experiences.

    I remembered my Amazon experience.

    I have recently changed my laptop and phone and each time I logged into my Amazon account from a new device/browser I got a security challenge. I had to enter a security code that was sent on my email.

    Friction during logging in

    This is inspite of me authenticating myself using my Amazon credentials –  login id & password.

    So why the additional step?  Why add to the friction of logging in?


    • Its a friction-less way of doing XYZ !
    • We have drastically reduced the friction in each transaction
    • Our platform provides the most friction less experience for ABC

    Am sure like me, you keep hearing how every venture and corporate is focused on reducing friction and there by making it a significantly better experience for their consumers/stakeholders etc.

    And I get it.

    If I almost always use an offers platform to look for offers near me on a mobile app, it should not ask me to choose a city, then location etc – it should just pick my location and show me the offers. I get it.

    Similarly, if my online or in-app payment process need an OTP and there is a way to automatically read the OTP rather than needing me to toggle from the merchant app to the messaging app and back. It is definitely so much cooler and easier.

    BUT, ALL FRICTION IS NOT BAD

    What I don’t get is how suddenly friction has become such a bad thing.

    Way back in my school days, we were taught in Physics that while friction caused wear and tear, it also was the main reason wheels work – friction prevents slippage and aids rotation. Snow chains for tyres – aid driver confidence by increased traction (apart from helping break the top ice layer).

    My current thinking on friction less experiences is as follows:

    • All consumers are not same. What is a great experience for some may be a concern for others (elevators vs escalators) . Hence it may be best to have varying levels of friction available for consumers.
    • Friction can help build consumer confidence – esp amongst users concerned about security
    • It may be useful in the on-boarding or early days of consumer-product relationship. As confidence builds, some more steps can be reduced. Like this recent experience where my Credit Card limit enhancement was pitched and delivered at the optimal moment.
    • Friction is also an industry level phenomenon. As an industry matures and consumer confidence builds, need for a faster, smoother way to do the same old task would become stronger.

    What do you think?

  • Why so serious ! Need for humor at work

    Why so serious ! Need for humor at work

    This happened yesterday – We settled down for a discussion first thing in the morning and a colleague says- smile guys, its a good day!

    But, it was a spirited discussion . And the smiles quickly vanished.

    We shared our views and debated. And I realised I was talking with a lot of emotional energy.

    I told myself, its ok  – because I am committed and passionate about this. But there was clearly another voice telling me – its not ok.

    And then something interesting happened later in the evening.

    I was reading Pegasus Bridge  June 6 1944 – By Stephen Ambrose and came across a section where it talked about the front in North Africa.

    pegasus bridge

    In particular the book was introducing Hans von Luck – a protege of Rommel – who agreed with his British counterpart to fight a civilised war.

    Every evening at 5 p.m. the war would stop. The Brits would break for tea and the Germans for coffee. They would then get on the radio and share the details of captured personnel and any messages these POWs may have for their families – usually messages confirming that they were ok.

    In one particular instance, the Germans learnt that the Brits had got a fresh supply of cigarettes. Von Luck offered to trade a captured British officer for a million cigarettes. The British countered with 600K. And a deal was stuck.

    But the prisoner refused to be exchanged because he insisted he was worth the million initially asked for !!

    I was shocked !

    These are men at war. They are willing to kill and die. Yet they manage to keep humour and civility intact.

    I am lucky to have read about this incident the same evening I was telling myself its ok to lose my cool. It has helped put things in perspective.

    I went back to my colleague and shared this story. Thanked him for opening the meeting with a request to smile.

    He has decided to make sure that every meeting he attends, he would put smile(s) as the first agenda item.

    And I am inspired to go a step further. To keep humor intact at the workplace – the place where we spend most of our waking hours does not need to be such a serious place.

  • Cash is not the enemy – Stickiness of Cash Part 1

    Cash is not the enemy – Stickiness of Cash Part 1

    Why is cash so sticky in our society?

    Many of us have argued for the need to build convenience, security and ubiquity for digital payments. And then cash would start receding. No debate there.

    But we forget that as individuals our brains are wired to go back to cues that are triggered at the sub-conscious level. We are not always the rational individuals economists would have us to be. Our decisions are influenced more by emotions.

    CASH IS NOT THE ENEMY

    To appeal at the emotional level, we need either a villain or a hero.

    While bankers and payment professionals would disagree with me, but for most Indians cash is NOT the enemy. Consider this:

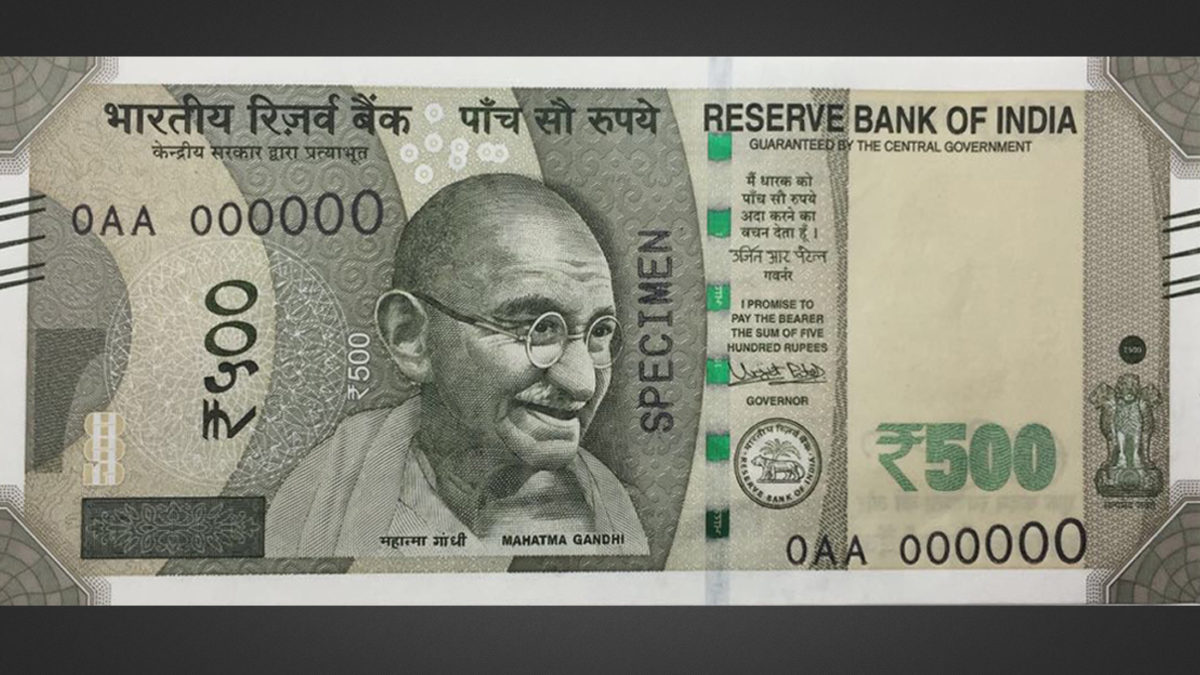
    • The currency carries images of Mahatma Gandhi, of the National Emblem and now of Mangalyaan etc. These are symbols of national pride. We are wired to feel proud to hold a piece of paper with these images on it.
    • We have traditionally celebrated an auspicious occasion with gifting loved ones with money. This association of gifting currency with happy moments is also tough to break anytime soon. Again deeply rooted positive connect.
    • When the Prime Minister announced the ban of old currency notes, the villain being chased was corruption. Not cash. So we never really took the storyline that cash is bad.

    I don’t think any country would even want to walk down the path of trying to build a negative connotation with its currency.

    Hence a story where cash is the villain may not work. We need something else to pitch Digital Payments at an emotional level.


    This is part 1 in a series of posts where I try to understand why Cash is sticky? What are the some of the obvious things, we may have overlooked in our zeal to digitize payments.

    Here’s part 2 , wherein I talk about why its a tough journey moving away from cash – too many choices and a hurdle-ridden on-boarding process.

  • Beyond Big Data – A Small and fast data example

    Beyond Big Data – A Small and fast data example

    Big Data is all the rage. Everywhere you go, any meeting or presentation one sits through, Big Data seems to be there.

    But there are opportunities beyond big data. E.g. how we handle small data fast.

    Here’s an example of small data that I experience almost everyday.

    In many corporate buildings in India, you would notice that you need to punch in the desired floor into a panel, which prompts you which lift-car to hop on to.

    Fast data ElevatorsSimple yet brilliant solution.

    You club the waiting passengers into specific cars by their desired floors. The average wait time is lower, the average travel time to your floor is significantly lower.

    And all the magic happens in a jiffy.

    The data becomes irrelevant soon (apart from being used by the algorithm for learning and further optimization). And in a classic example of not-so-big-data. But the fact that this small set of inputs from users is taken, crunched and optimized for elevator allocation in almost real time makes it so amazing.

    Small but fast Data.

    In Data-led-solutions, the 4 V framework helps evaluate potential impact:

    • VOLUME – Available Data size. Is it big enough to build confidence in predictive models?
    • VERACITY – Data-accuracy: How accurate is the data that we feed into the system
    • VARIETY : Are we collecting data from multiple sources? What all do we know about the scenario
    • VELOCITY : What is the speed with which we process and move data? How fresh is the data as it moves across the value chain?

    This small-data use-case is very high on the data-velocity parameter and I guess just solving for data-velocity has allowed for the solution to be adopted.

    So in summary, there is life beyond Big Data too. 🙂

    What do you think?

  • Immediate reactions to the banning of Rs 500 & 1000 notes

    As Anshul & I sat listening to the PMs announcement and then all the experts on CNBC, we couldnt help discussing what all must be happening around the country in the next 72 hours.

    500-1000-note-banWe are surely living in interesting times.

    Managing high denomination notes:

    • All secret saving places in the homes/offices/godowns will be cleaned and reviewed today.
    • Piggy banks of kids will be broken tonight. And parents will have a hard time telling the kids why they cant wait for the kids bday
    •  Many would queue up at petrol pumps to get their cars tank-fulled.
    • People with blackmoney would already be approaching hospital owners and petrol pump owners to help them convert their black money into white.

    Getting cash with lower denomination:

    • Ppl would queue up infront of ATMs for withdrawing Rs 400/- . Multiple times. Confirmed.
    • People would watch their cash spends like never before.

    Moving away from cash:

    • Payment apps will see a sudden spike in downloads and activation over tonight tomm.
    • Wallets will be topped up. Card activation rates will show a sudden spike, esp on the debit cards
    • Uber and Ola will have a field day as autos & kaali-peeli wont be preferred. Pls expect surge pricing.
    • Most small merchants will see a dip in transactions next 2 days. They will teach themselves how to accept cards.

    Banks & Payment Providers

    • Opportunistic Banks would send SMS & emails to customers to activate their debit, credit prepaid cards.
    • The CASA books will see a sudden increase as the rate of deposits will be higher and faster as compared to rate of withdrawals from the account. Few dormant savings accounts may become active.
    • Merchant acquiring teams will suddenly be seeing incoming pull business rather than push.
    • Jandhan account activation rates will be very high.

    Ripple Effects

    • Like Future Group, many merchants will be open almost till midnight tonight. Grabbing whatever opportunity that exists in this situation.
    • Zomato & food ordering apps will see a growth in business. Their market share of each partner restaurants overall revenues will increase.
    • COD rules will now need to incorporate not just pincodes but the order amount too. COD may be suspended for the next 2/3 days.
    • Property deals would be on hold till the new norm of the market emerges. Or till enough of the new notes find their way into the parallel economy.
    • Odd jobs at home will be postponed. Big hit to the daily wages skilled earner. They would be forced to ask their clients to deposit money into their Jandhan accounts.

    Funny Thoughts

    • Patanjali would need a new theme for their campaigns. Kaala-dhan (black money) story would just not fly
    • Marriage season gifting needs more innovative ideas. Envelopes don’t cut it any more.
    • How will the rich temple trusts manage the shift towards less-cash?
  • Good rules should be designed for higher adoption

    Good rules should be designed for higher adoption

    How do we drive adoption for rules in a community, or even at a country level ?

    Should a good rule be designed to make it easily enforceable too?

    I think it should be.

    If we want to build a society where most follow the rules, enforceability should be an important criteria.

    To decide whether a new rule should be introduced or not. Whether an existing rule needs to be modified or scrapped.

    Why?

    It is my belief, that when we have rules that can be easily broken without any consequences, it sends a signal to the community. And this signal usually leads to a gradual loss of respect for the law of the land and for the fellow citizens. Read the explanation of the Broken Windows Theory

    Effective rules implementation

    Let me explain with an example of two rules, which most of us in India are familiar with

    • Front seat passengers should wear seat belts while traveling in a car
    • All vehicles should have a valid pollution-under-control (PUC) certificate

    While both these were introduced in the last 20 years or so in NCR, the first one has seen significant levels of adoption whereas we all know that very few cars and bikes have a valid PUC certificate.

    Why?

    If you ask me, the reason is very simple.

    For seat-belts, the fact that you are complying (or not) is visible each and every time you are driving. Any traffic-cop who sees you not wearing the seat belt can pull you over and issue a challan. So you run a very high risk of being punished if you are out on the road w/o wearing your seat belts.

    Contrast this with the pollution certificate rule.

    A traffic cop on the road has no clue if your vehicle currently has a valid PUC certificate or not. Hence the cop would rarely pull you aside asking for the certificate. It is usually asked for when you have already been stopped for some reason and they feel that they might put more pressure on you if you are w/o the PUC. Hence as car owners, we are usually not very afraid to drive w/o this certificate. The risk is just too low. And hence very few cars actually have a valid PUC certificate.

    So while almost everyone knows that the laws need them to drive a non-polluting vehicle, very few actually end up doing so.

    And I think its very simply just the issue of how easily the rule can be enforced.

    In my opinion we should have few rules, but all should be enforced strictly.

    What do you think?

  • Search Vs Social – the long tail of ad revenues

    Search Vs Social – the long tail of ad revenues

    Google and Facebook together took away 64% of the total US online advertising spends. And Facebook had around 65% of the overall online display ad-spends. These are incredible levels of consolidation in the ad spends among the leaders.

    search-vs-social

    Enough has been said and discussed about

    While one cannot argue with the numbers and the line of reasoning, I somehow felt that this discussion has ignored the long tail of ad-revenues or the lead generation aspect of these platforms. These reports are focused on big co’s with big media budgets who may typically have brand-building as the key target.

    Let me explain this in some more detail.

    There is no doubt that for Google or Facebook, the big marketing dollars would come in from big spenders like Ford, Coca-Cola & Pepsis, Samsung, Levis, Red Bull, Wells Fargo, Amex etc.

    But if we were to evaluate these platforms from a start-up point of view (small budgets and maybe need to do lead generation instead of brand building), the story is very different.

    1. Social targeting is profile based, too many bidders

    On Facebook, the same user may be targeted by multiple brands, because there is hardly any other context. E.g. a 35 yr old male who lives in a metro and has liked multiple lifestyle brands would be a good target for many.

    We do NOT have additional context for the specific session on FB when the ad is being displayed. One FB session is hardly different from another in terms of the intent or maybe when mood based marketing algorithms evolve things would change.

    This means, each of the target users FB session will appeal to all the brands. Multiple brands would be vying for that same ad-impression, which in turn means higher bid rates and CPMs etc etc.

    And this means that small budget advertisers would be elbowed out of the platform by big budget cos.

    While this article on Forbes also has the same conclusion, the logic used is very different.

    2. Search has deep context, removes non-relevant advertisers

    Search on the other hand has hugely relevant context. E.g. a user looking for Mortgage loan options on Google will be targeted by Financial Services brands vs someone searching for Fine Dining Options in India.

    And this means, that as an advertiser you are just competing with other competitors or maybe some adjacent industry players.

    Bid rates would be lower and even with small budgets one can get the message out to a relevant audience.

    3. Lead qualification is efficient on search

    If one is looking at online advertising for lead generation, chances are search may be a better platform.

    Before the Facebook fans pounce on me, let me qualify my statement.

    Many of us run “boring” ventures – we pitch services that consumers may not want to share. And/or we do not have the creative bench strength to get a funny/interesting message out. Our content strategy may still be a WIP. Realities of life.

    If the message/ad we create has low viral coefficient (i.e. we do not expect people to share it much), Facebook may not be the best platform. Coz then we are burning marketing dollars to talk to a prospect who may not be primed for our services and who is also not helping spread the word.

    Google, on the other hand is a very different story. If a consumer is online actively writing into the search box key words that resonate with your offerings, you may have a very interested customer. Intent is high.

    Also, my guess would be that the long-tail ad-spends are stickier.


    But all this is just my 2 cents on how small ventures, start-ups and SMEs should look at spending their advertising money online – across the broad theme of Search Vs Social Marketing for the long tail in particular.

    What do you think?


  • Unit Economics in the times of Auction Marketing Models

    Unit Economics in the times of Auction Marketing Models

    Unit Economics is all we hear these days in the consumer technology world. Unfortunately for many start-ups seeking venture funds, this is the biggest hurdle they need to cross to build a strong case for their business.

    What is the concept of Unit Economics

    I will not go into the definition and relevance of Unit Economics. That’s well documented here and here. Or just Google it.

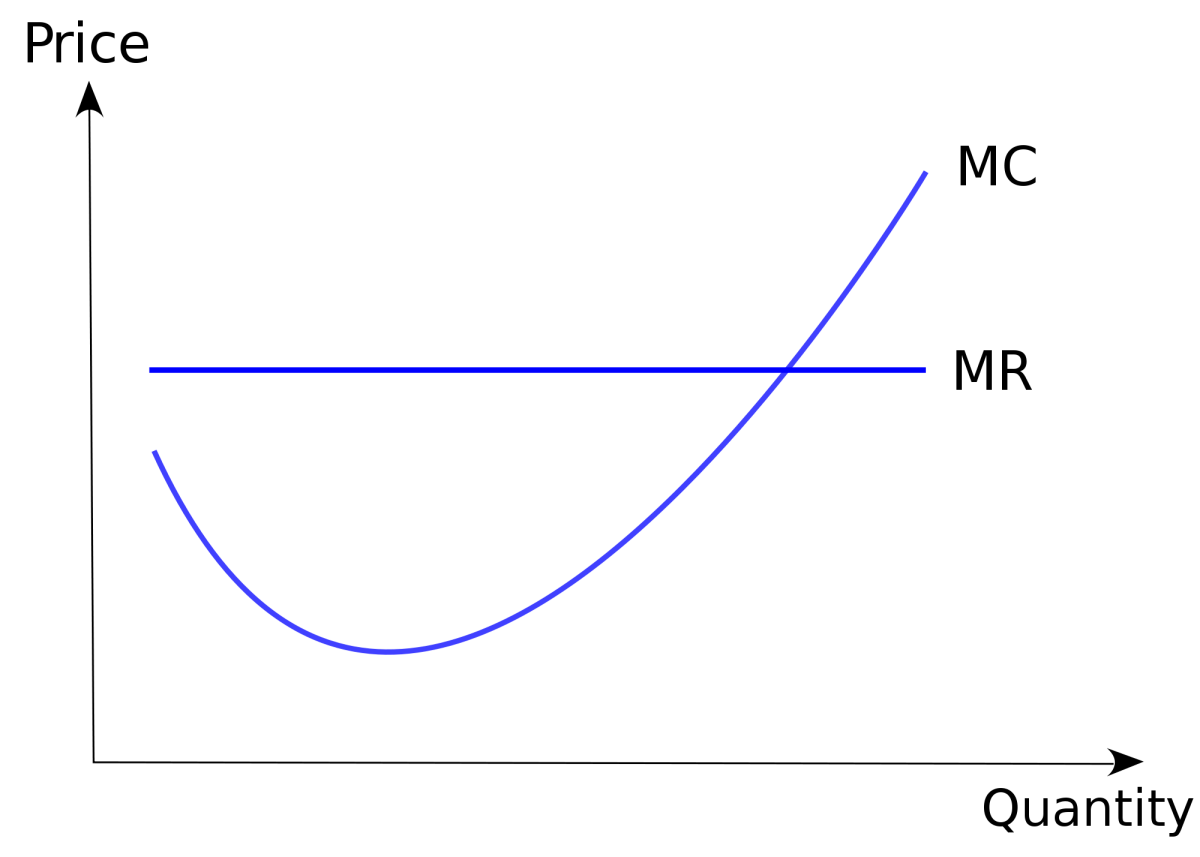
    Lets refer to Microeconomics 101 for our discussion – Marginal Costs(MC) and Marginal Revenue(MR). We all know that its a healthy sign if Marginal Revenues are higher than Marginal costs. And this delta (MR-MC) is what is unit economics.

    On the other hand, if we are losing money on each transaction, either we see the losses reducing or we stop growing transaction volumes.

    At least rational individuals would choose to do so. Or so goes the basic Economics assumption.

    Unit Economics in web/mobile start-ups

    1. Marginal costs are volatile

    A big chunk of a start-ups costs is the customer acquisition cost. ( I am excluding businesses with very high repeat volumes in early days where the operating costs contribute heavily to the overall transaction costs).

    Most start-ups need to market their products and services. They are in a continuous state of transaction ramp-up along with concurrent improvements in experience or efficiency.

    And in a world where most advertising/marketing channels are bid/auction model driven – this translates into the marginal costs being highly volatile. How volatile?

    • In the early days when you don’t have the luxury of brand-pull or of time, almost 60-70% of transactions may be coming from Google Adwords/Facebook/Ad-networks. Meaning 60% of your business is not insulated from pricing shocks.
    • Bid-rates may vary as much as 30-40% to maintain the same positioning. Maybe more, if there is a competitor who has just raised a round. Also, if you are competing in a category where big brands play, anything can happen. E.g. At Deal4Loans, we had seen bid-rates on our key-words jump significantly every time a competitor raised venture money or a bank launched a new digital campaign.
    • Add to this that the conversion-rates of your campaigns have not yet stabilized. Remember, these are early days, you are experimenting on your landing pages, and funnel optimization is still underway. So the final cost per account gets even more volatile.

    2. Customer Pricing is relatively in-elastic

    Theoretically, if you could pass on the burden of increased bid-rates and hence the ups/downs in marginal costs on to the consumer, your unit economics would be safe. The neighborhood vegetable vendor who has daily-prices does exactly this and is hence able to retain his margins.

    Unit Economics

    But this is rarely possible. Pricing is just not that elastic.  Most mobile/web start-ups can not /do not change prices so frequently.

    3. Marginal Cost CURVE is UNPREDICTABLE AND NOT SMOOTH

    We know that the bid-rates can inflict wild fluctuations(as seen in pt1) in the cost of acquisition, thereby making it unpredictable. But a bigger challenge is that the Marginal Cost curve is not smooth.

    Realistic MC MR Curve

    One rarely finds gradual changes in marginal costs with increasing through-put. It happens in unpredictable steps. Here’s why

    • Each fluctuation in effective bid-rate leads to drastic ups/downs
    • As a start-up you are experimenting with multiple channels. Success in any one will bring down the blended MC immediately.
    • Referral/Viral coefficient and % of in-bound of the campaigns can impact the costs significantly. e.g. One PR mention may bring in huge self-select traffic.
    • SEO traffic which is typically very predictable can also swing wildly with a new Google update as we saw with Penguin and Panda.

    So what do we do?

    • Keep Experimenting. Do know that customer-acquisition at optimal price is a moving target. You are never really truly there. It can always be better.
    • Invest early in content. In-bound has significant ripple effects.
    • Raise money but don’t throw it all on branding. Consumer memory is short lived. Discover and test more channels, unlock access to more segments.

    I would love to hear from bootstrapped ventures as to how they are/have handled the customer acqui costs. What worked, what didn’t?

  • Public policy, ripple effects and feedback loops

    Public policy, ripple effects and feedback loops

    I have always been intrigued by product design and by extension policy design (& implementation). If the government were to look at itself as a start-up technology venture, the policies, schemes and guidelines issued by the government would possibly be the “products” of this venture.

    And like any good product manager, one should study not just the immediate impact of change(s) in product design but also the delayed and maybe stickier changes in consumer behaviour.

    And that is what I want to share with you today.

    Shift in dietary habits due to Green Revolution

    Sometime last month, I was visiting an uncle of mine – someone who is in his mid 70s, reasonably fit, exercises regularly and has borderline diabetes. While we sat at the lunch table, I noticed that he had multiple other grains in his roti as against mine which was from just wheat atta. It seems most physicians recommend adding ragi, chana etc in your atta mix as a healthier alternative.

    And that’s how our conversation began.

    Wheat Green Revolution

    And what came out was quite surprising for me.

    It seems in their childhood days in villages of western U.P., wheat was not the staple grain. Infact it was considered a delicacy and wheat-chapattis were made when they had guests over. And he comes from a well-to-do farmer family. This was not because of economic constraints, it was just how things were.

    So as the elders started talking about this significant shift in probably the most important component in a typical North-Indian meal – roti – what emerged was that the shift was triggered by the Green Revolution in all probability.

    This lunch group which included scientists and government employees, agreed to the following sequence of events:

    • Wheat was one of the chosen candidates for green revolution . Though am very curious to find out why?
    • Government stepped in on the supply side with higher yield varieties, irrigation support etc
    • It also created artificial demand by setting up floor prices thus encouraging farmers to grow wheat. Making wheat a critical component of Public Distribution System also ensured a big buyer for wheat at these prices. This in turn ensured that a higher percentage of land under cultivation now got sowed with wheat
    • This brought the otherwise-considered-premium grain into the middle-class households at a very affordable price. Imagine if suddenly, you find yourself able to afford an item which for years or maybe generations was considered premium, chances are you will buy more of it to feel good (my assumption)
    • And they all started eating wheat more, skewing our diet heavily towards this singular grain in North India.
    • And the subsequent generation(s) like ours has come to believe that our rotis have always been a wheat-only product. Coz wheat rotis is what we ever saw.

    Am also very clear that India’s self-reliance on nutrition has been contributed heavily by progress on wheat and rice. So there’s no doubt that this has worked as planned.

    The fact that wheat may not be the healthiest grain is probably something new. Gluten intolerance was probably unheard of during the Green Revolution.

    But with the new facts before us, should the government re-evaluate its focus on just a handful of grains in its policies.

    What if, the support prices on wheat are relaxed a bit? What if other “healthier” grains are encouraged similarly? Will the cost of managing supply chains and warehousing for multiple grains offset the advantages of a wider-spread in our diet?

    Many questions and I don’t have any answers.

    Low availability of fodder for cattle

    Ask any elder who has seen standing wheat crop in the fields now-a-days vs in the old days. One thing they would tell you is that the wheat crop is now stunted. Its much much shorter.

    This am told, was probably one of the biggest breakthrough in developing High-Yield-Varieties. The nutrients and water is no longer “wasted” in the growth of the non-grain-yielding parts of the crop.

    But on the flip side – this has increased the cost of cattle-management for local farmers. Why?

    There just isn’t enough fresh fodder for the cattle. The non-grain part of the wheat crop was used as fresh and dried fodder for the cattle that the farmer had at home. This is gone.

    As my friend (who runs a dairy farm) tells me, procuring fodder is now a big challenge in most regions.


    I am not an economist or an agriculture scientist and probably have understood just a very small part of the whole picture here.

    But I learnt few important lessons from this lunch conversation :

    1. There are usually multiple ripple-effects of any new policy change ( or product change)
    2. While the product may deliver on the core metrics initially identified as measurements of success, we should zoom-out and ask ourselves, what else has changed
    3. I should start eating healthier. Right now  🙂
  • Payments are a critical piece – Digital Banking ToolKit

    In India, digital and mobile Payments is a really HOT space right now.

    • HDFC Bank introduced PayZapp which intends to be the gateway for all m-commerce transactions, with incremental offers as the initial incentive
    • ICICI bank introduced “Pockets” – a way for even non-ICICI Bank customers to have access to mobile payments
    • Axis bank launched Ping Pay and Lime
    • 11 new Payment Bank Licences have been issued. This not only includes some of the bigger telecom players but also the likes of PayTm.

    All this action is triggered by multiple factors including a huge opportunity to move transactions away from cash. In the fact that ecommerce is booming and so is the comfort that consumers have in paying online or through mobile. Mobile, smartphone and 3G penetration is booming etc etc.

    But from a bank’s perspective, payments are critical.

    Why?

    Payments are high-frequency use case

    You would probably take 3.5 loans in your life.

    Your salary gets credited into the account once a month. If you have a SIP instruction, the investments may also happen once a month.

    You withdraw cash probably once a week.

    But you make maybe multiple payment transactions everyday. And in most cases, banks do not have an idea of the payments we make.

    More transactions allow banks to have more interactions with their consumers and hence move a step closer to being an Everyday Bank (Accenture coined this interesting term to bring banking into consumer’s day-to-day activities).

    Payments provide rich-context

    During my brief stint in the Life Insurance industry, the key challenge was that post acquisition, there is not much context to go back and start a dialogue with the customer.

    The same is true (or will soon be true) for banks that miss out on the payments. Access to payment level data gives so much deeper insights into the consumer.

    The bank understands where do you spend (which markets, which segments), when do you spend, your typical ticket size etc. This is really powerful data, which can help generate insights into customer segments and their needs. E.g. a banking customer who pays school fees (for her kids) online has told the bank that she might be a good target to be pitched Children Plans (life insurance).

    It can also help the bank design better products that resonate more with the consumers.

    Payments will see sticky behavior

    In the early days of Digital Banking, it was said that the bank which manages to get Bill Payments on to its account will be a sticky account. If you can get the customer to map his utility payments etc, you were on a path to be the preferred banking account.

    Why ?

    Because these are important transactions yet not something customer wants to spend a lot of time on. Hence if he gets used to a specific platform/UI – until and unless something changes drastically, the customer would not move. Same reason why I am so loyal to PayTm ever since they made it so easy to pay bills and do set-top box recharges.

    The bank or service provider, which onboards customers to a frictionless platform will be tough to unseat.

  • Marshmallow Test and Insurance Marketing

    I spent the last week reading up “The Marshmallow Test by Walter Mischel”. And while the book is a fascinating summary of key findings (and some of its applications) from Walters more than three decades of research, I found some of it is relevant for how we look at Insurance Marketing and Sales.

    What is the Marshmallow Test

    Walter’s team designed a test for pre-schoolers where the kids were asked to pick their favourite treats from Oreos, marshmallows etc. One of the treats was placed in a tray in front of the kid on a table. The table had a bell, which the kid could ring to bring back the researcher. There was another tray which had two of the same treats, on the same table. The kid was told, that the researcher needs to step out. If the kid wants to bring back the researcher she can just ring the bell, but then he/she gets just one treat. On the other hand, if the kid waits for the researcher to return on her own, she could have two treats.

    As one would expect, there were all sorts of experiences that were witnessed in this experiment – from kids who waited easily, to those who found it very painful, to even those who ate the cream from all three Oreos and kept it back as if they had not been touched at all :-).

    Walters team ran these tests and tried to understand how the human mind manages self-control, Takes decisions which can postpone instant gratification. What techniques work and which ones fail, consistently. And in all of these interesting findings, I found these as most relevant for Insurance Marketing.

    Me Vs Them, Now Vs Future – HOT & COOL Minds

    In multiple versions of the tests it was discovered that when asked, whats the logical thing to do for someone who is given the option of 1 treat now vs 2 in the near future. Every kid said that any smart one would wait. And interestingly when the same kids were asked, what would you do – most of them responded by saying “I would take the one treat”. Walter believes that this is due to what he calls the HOT and COOL brain system getting activated. When its a hypothetical situation that involves someone else, the cool mind takes over – it is good at coming up with rational and logical answers and hence every one knows that we should wait. But when the situation involves us and in the present, the hot mind takes over. This is where it becomes tough to manage the temptation.

    The book talks about another experiment conducted by Hershfield, where in participants (in their mid twenties) were asked to create a digital avatar of themselves. For one set of participants, they were shown their regular avatar and asked how much would they invest in retirement planning. And the other group was shown their own aged avatar (aged mid-sixties) and asked the same question. Surprise surprise, those who saw their future self said they would save 30% more than those who saw their normal self.

    marshmallow test insurance marketing
    Source: HBR (link below)

    Read about this interesting study on how we make better retirement planning decisions here on HBR.

    This tells me few things (& I would love to hear what you read into the findings)

    1. Insurance purchase decisions are very similar to the Marshmallow test conditions. You forego immediate spends for deferred benefits.
    2. Walter discovered that the specific tactics that were adopted by each kid who waited (for the better rewards) fell into a generic category – Cool the now, heat the future. Which means, reduce the temptations of the immediate future and build temptations around the choice of waiting. Sounds logical, and there are good insights for Insurance sales and especially renewals. Buying on monthly installments is easier as the psychological barrier is 12 times higher than when buying an annual policy. Auto-renewal (Standing Instructions or Auto Debit) is better for persistency, as the consumer is not subjected to the same choices every year.
    3. Personalization – Creating Insurance ads that showcase a happy retired life may not trigger purchase decisions, because the consumer may or may see himself in the lead actor of the TV ad. If he doesn’t, chances are he understands the theory of why insurance is needed, but when presented by a choice to buy, he would forego. And this infact has been the experience of most life insurance products. We have only moved a step in this direction with calculators and personalized models for generating scenarios. But they are far from effective in building a true connect with the future self of the user. Calculators and models talk to the cool mind, what we need are ways to get the buyer involved actively in the future self. And decide now in favor of the future self or future selves of his/her dependents.
    4. I see a bright future for digital in Insurance marketing – we have been going at it in the wrong way. Cheaper term plans is not the only opportunity here. Disintermediation and cost-saves is just one slice. The Insurance agent was selling successfully not only coz of the trust & proximity he has with customers. Maybe he can narrate stories from closer home, talk to the customer by giving vivid examples and building scenarios where the customer can easily imagine himself and his family.

    Like all interesting studies on behavioral economics and psychology, I feel Marshmallow Test is a great set of hypotheses to bring into the marketing themes and design of campaigns.

  • Showing Contact Addresses in Google Maps

    Quick Summary:

    Here’s a small product feature recommendation for Google Maps on Android. Currently when I am in Google Maps and typing in the search box, it throws results that match with Google Places directory on the web. If it also throws matches with local contacts in the phone (or Google account) that have an address field added, it will ease usage.

    Google Maps & Contacts
    Background:

    A quick background will help understand the use-case much better. I was traveling to Jaipur and wanted to go to my friend’s place in Bani Park. I had asked him for his address the day before and stored that in the phone’s contact against his name. Now when I was close to Bani park and looking for exact directions to his place, I had to

    • go to the Contacts,
    • search for his name,
    • View and copy the address,
    • Close Contacts and open Google Maps,
    • click on search(in GMaps) and paste the address (without the door number etc),
    • See the matching list of places from Googles Places directory,
    • Choose the right one and get started

    Recommended Solution for showing contact addresses in Google Maps :

    It would have been so much easier if

    • I go to Google Maps
    • Click on search and type the friend’s name
    • IF there is an address field against it, gets thrown up
    • [CHALLENGE] – Smartly remove the part(s) of address like door or flat number and match it with Google Places
    • Get started

    Better still would be if
    GMaps and contact addresses
    Once I have used the (text based) address for directions inside maps for the first time, it asks me to “pin” the place on the map when I reach my destination,so that an accurate latlon (latitude longitude) can be entered in a hidden field against this address.

    If this pinning of a text address is done, it can add more wow – as soon as I open up Google Maps at a particular location, it can show me my pins in the vicinity – no more typing or searching needed – just choose the pin for directions and get started.

    What do you think?

    Is this something that would make your GMaps experience better? Do let me know in the comments section below – will love to hear your feedback.

    #Android #GoogleMaps #GMaps #Google

    Update – Google Maps now has this feature live !

    And am thrilled. Not just as a user. But also as a product manager, that a feature that one envisioned has been found useful and implemented.

    Here’s how it looks now. Interestingly, the match from the address book is right at the top.

  • Thin Mobile App or a Fat one – Digital banking toolkit

    Mobile is the new frontier and banks know this well.

    Amongst the various choices to make as part of the bank’s overall mobile initiative, is the decision around the structuring of mobile app(s).

    Thin App Vs a Fat App.

    These might sound strange terms especially in reference to mobile apps and no, we are not talking about the size of the app in MBs.

    A Thin Mobile App is a niche solution available for select instances or customers, which allows a small subset of activities to be handled.

    On the contrary, a Fat app is one where all the possible features and functionalities are available in the single app.

    Banks have chosen to tread either of the paths. E.g. ICICI Bank has multiple apps in the playstore and HDFC Bank has just one main app.

    Bank Mobile App - Fat or Thin

    As one would expect, there are pros and cons of both, and I am listing a few here that come to my mind.

    Attribute Thin App Fat App
     Clean UI  Easy to deliver  Needs design assistance
     User Engagement  Higher – as less distractions  Lower as many features irrelevant
     App Marketing  App adoption slows as marketing dollars split across multiple apps  Overall downloads look better as one single app
     App Development  Becomes complicated with multiple apps in market  Easier since tracking just one app
     Channel Migration  Depends on how the bank approaches it   Depends on how the bank approaches it

    I personally feel, more than the final choice, it is the reasons that drive the choice which are important e.g.

    • It makes more sense to have a separate thin mobile app, if there is a unique customer segment that seems to have very different transaction or enquiry profile as compared to the others. E.g. Retail bank customers vs SME business owners
    • Building Traction. Many banks want to keep their mobile banking app for transactions only and do not see value in building any pre-login use-case. This makes the mobile adoption target so much tougher as there has to be a very precise value that the customer foresees in using the mobile platform for transacting. Plus its a two stage goal, get downloads and then get usage. It might be useful to break it down into easier goals, get downloads by providing a use-case even if its a pre-login e.g. offers on debit and credit cards. And then get the customer who already has your app to start using it for transactions.

    What do you think?

  • SMS is reborn as an acqui channel in the Smartphone age

    In the early days of Deal4Loans, we used to get a lot of traffic and leads through SMS campaigns. Especially for products like Personal Loans (Simple pitch and high-urgency in a need based product)

    SMS reborn in smartphone ageDuring those days, NDNC (National DO NOT CALL) list was not introduced and there were very few players who were sending bulk SMS for lead generation. Response rates were high.

    Market quickly figured out that this was a cost effective and easy channel to scale up. A tsunami of SMS campaigns started to happen and finally the National government had to intervene with its NDNC initiative.

    And while SMS acquisition campaigns have largely died out, it seems to be back again.  And with even more potential.

    In a recent campaign we closely observed, a bank reached out to a select base of consumers through SMS and emails. The resulting traffic on the portal was significantly higher in case of SMS.

    Why?

    Apart from all the other factors (higher delivery rates, targeting time of intervention), now most recipients have a 3G or Wifi enabled smartphone, where CTAs are simple. This campaign had a short URL taking to the Landing Page after a crisp text talking about the offer.

    Lesson learnt:

    If you can withhold the temptation to abuse your mobile registered users, SMS can deliver amazing results even in marketing campaigns.

  • 3 tips for New To Bank Acquisitions – Digital Banking Toolkit

    Why Online Acquisitions

    Acquiring New To Bank (NTB) customers is a key agenda for most Digital Heads at Banks.

    Its only logical that online acquisition budgets are getting bigger, given the following:

    • Consumers are spending more and more time online. Digital is the best channel to start a dialogue
    • Digital channels are tracked exhaustively. You can measure the return on each dollar spent.
    • Digital channels allow data to flow at higher speeds. This could translate into better context, targeted products, straight-through-processing, upfront checking of applications etc etc.
    • Tablets have provided the ideal form-factor to do an assisted digital sourcing, as has been proven by the success of ICICI Bank
    • Regulatory changes are also making it easier to acquire online – Aadhar database, eKYC, wet signatures to go away in some instances etc.

    Here are 3 seemingly simple tips for anyone who is doing NTB acquisitions today at a banking set-up.

    Choose the right on-boarding product

    choose-productWhich product will you focus on to get more customers into the bank?

    Many would say, we do not have a choice as each business line would be relying on the support of digital channels. Be as it may, it might be prudent to take a step back and understand the advantages of choosing a particular product for consumer on-boarding vs another.

    • Do we reject a lot of applicants for this product. Typically in case of credit cards and most loan products, the rejection rates are high and hence we need to sieve upfront to reduce the cost per lead or cost per account. Are there other products in the portfolio which have lower rejection rates e.g. most liability products may fall in this category
    • Does the product start giving me more data and insights about the customer? Can I build strong contexts to pitch the next product. Any payment product would be a good bet as it starts building a lot of relevant data points about the customer.
    • Is this being sold or the customer has a well articulated need? Loans should see a higher conversion as against credit cards because the customer has a need. But the scenario may change if the card is free and loaded with offers.
    • Is the process straight-through? If not, how many steps are there? The higher the number of steps, lower would be the conversion rates.
    • Competition – given that you are not the only bank trying to talk to the customer, the kind of marketing money it takes to interrupt a customer would increase for the segment with higher competition. Back in 2007 the bid rates for Personal Loan keywords moved almost 100% in less than 6 months. Every bank in India was focusing on acquiring Personal Loan customers.

    Manage the Drop-out funnel

    With all the tools available for tracking, doing A/B testing it is so much easier than before to manage the drop-outs in the acquisition channel. Over the years, industry has also learnt and created a best-practices library. Use it. E.g.

    • Acquiring through partners who have data on customers is more efficient and reliable. This is why most banks are exploring SME financing through ecommerce platforms.
    • Allow applicants to save applications and continue later. Across channels.
    • Build for a true OmniChannel experience. As the customer journey will definitely toggle devices
    • Provide for assisted filling of forms. What might sound simple & easy to you may be confusing to others
    • Authenticate the communication fields upfront (email, mobile). This allows you to follow-up on leads more proactively.
    • There are no permanent rejections – a customer who is not eligible today may be eligible tomm. Except may be those who are already over age :-).

    Build data-led acquisition platforms

    Data - Led AcqisitionsWhat has changed significantly in the last decade is the amount of data prospects and customers are generating across various channels and touch-points. The future (if its not already upon us) of digital acquisitions is data-led.

    E.g. acquiring SMEs for working capital financing can happen in multiple ways:

    • Bidding on search engines for loan keywords
    • Putting up banners on B2B portals
    • Showing banners to specific SMEs on a B2B portal basis some cuts
    • Deep integration with portals to get fresh data about SME’s transaction, reputation, growth trajectory etc.
    • And so on.

    Its easy to see that as the richness of data improves and also its freshness, the credit decisioning becomes better.

    But this is not easy to do. It requires bringing together credit , product and digital teams into a room and understanding clearly the opportunities ahead of us.

    Some banks are already working hard to evaluate the new data-points available and calculate their influence on the traditional credit models. Its a matter of time before this becomes the new normal.


  • Easier to be Krishna than to be Arjun

    Easier to be Krishna than to be Arjun

    The other day, my mom shared a powerful and thought-provoking quote, that she had just read.

    It’s easier to be Krishna, than to be Arjun !!

    And she went on to explain, that being Krishna requires one to look inside and discover the highest qualities that each of us are bestowed with.

    But to be an Arjun, one needs to be full of faith.

    Infact have so much faith and trust, that you see a Guru in your friend, who then becomes the Krishna in your life.

    Krishna Arjuna

    Its a very powerful thought.

    To be able to trust someone or something so much, must infact be very liberating.

    Coz then you surrender all your worries, doubts and fears.

    I guess that’s why our ancient traditions laid so much importance on the role of a Guru.

    And its definitely true in our corporate lives too.

    We all need mentors.

    And for mentors to be effective, one has to let go of all fears, doubts and insecurities and share what we truly feel.

    Open up to our mentors.

    And most importantly, surrender.

  • Uber and Free Market Economics

    Uber has changed the way we travel within cities. On a recent trip to Jaipur, the first thing I did on reaching the city, was to top-up my PayTm wallet to get going on Uber. (yeah no card-on-file yet 🙂 )

    Uber Free Market Economics
    Uber Jaipur

    And over the next 3 days I took more than 12 rides across the Pink city. Here are some of the interesting observations I had:

    • Jaipur is really a small city – Only one ride was over Rs 100/-. All others barely crossed the Rs 75/- mark. Given the distances are not too much, the per ride fare is expected to be low. This is a critical point because the supply-demand balance can be easily titlted in a small-population. Also the per ride metrics are sensitive to even the slightest changes.
    • Free market economies tend to be cyclical – Almost all the drivers I spoke to talked about the good old times they have had, driving around as Uber cabs upto almost 6 months back. It seems back then Uber was super aggressive in signing up cabbies and were paying as high as Rs 1800/- per day. Guaranteed. This came down to 1600, 1400 and now is at 1200/-. And its all because of the immensely huge supply. Most cabbies now complained of getting too few rides on a daily basis. Add to that the low average per ride fare and it is clear that this city needs volume of rides to be high. Or to quickly reach an optimal sweet-spot of supply and demand match. As the word of tough times (for the cabbies) is spreading,  fewer are joining and many who had joined Uber are reportedly quitting it. Some can’t even pay their loan EMIs.
    • There is no consistency of vehicle experience – I got from a Nano to an Innova under UberGo. Firstly, UberGo is where most customers go, hence even cabbies are registering themselves as UberGo. So you are better off choosing an UberGo. The Innova guy said that he wasnt getting any rides so he switched from UberX to Uber Go. Also it seems you make the same per ride across both categories. Hence UberGo seemed a logical preference. The Nano guy was proud of his decision, he claimed that he would recover his investment much faster. And thats true. I think this is a classic example of how the market evolves when its close to a free market.
    • Drivers understand and give importance to rider feedback – I have never seen so much sensitivity from an Uber Driver towards the feedback/rating. To have been able to crack this is really commendable on Uber’s part. The drivers have strong appreciation for this feedback being utilized for giving them ride bookings. Again, there might not be a completely transparent system but the fact that information and feedback is flowing across the supply and demand side, is strong enough motivator to influence decisions.
    • Locals are avoiding taking own vehicles – Lot of areas constantly face bad traffic due to construction activities. Parking is a challenge. Most of my local friends have either started using an Ola or Uber over self-drive or are seriously considering to do so. Atleast till the fares are this low !

    Update:

    And back in Delhi.

    • There was a surge charge of 1.9X due to high demand and unmatched supply I guess. This allowed UberX  guys to also pick up UberGo customers without formally registering into the UberGo. Complete reverse of what’s happening in Jaipur. I guess Delhi customers prefer the more spacious UberX and there is sufficient demand therein.
    • The first cabbie who picked my request, called me and asked me where I need to go (instead of asking me where to pick me up from), and hearing my destination – declined. Just put the phone down and on my Uber screen I was back at fresh request. No way to even go and give feedback on this bloke ! So I guess Delhi cabbies have a hack to the feedback-driving-behaviour loop also. Land of Jugaad !!